Showing posts with label Risk. Show all posts

Wednesday, January 18, 2017

Government of the People….?


Poor government can be
ruinous...

"The penalty good men pay for not being interested in politics is to be governed by men worse than themselves."

- Plato

Saturday, November 26, 2016

NCUA: An Agency at the Crossroads...


We have been talking over the last few days about
Change must start at the top....
change at NCUA.  If change is needed at the agency, think we all recognize significant, serious change must come "from the top" - from the NCUA Board. 

The NCUA Board approved the "new" five year  "Strategic Plan" for the agency in September.  

Look to see if you believe the new, proposed NCUA Strategic Plan is a serious document - for it is the Board's plan. [here's the link - page 12]

Thought you might like to also consider a few excerpts from a recent opinion piece in the American Banker Magazine. The writer is Richard J. Parsons, a former BOA exec:

"When a bank fails and the resulting loss to the FDIC crosses a certain threshold, regulators are required to write a material loss report (MLR), explaining why the bank in fact failed. Well over 100 such MLR's have been written in the past few years."


"... the banks' examiners almost without exception gave these institutions good to excellent CAMELS ratings nearly right up until the point of failure."


"Start all the way back at 1979 - the year the CAMELS system was developed - and the total number of bank and savings and loan failures is now north of 3,400 institutions, including 470 that have failed since 2008.  The evidence of more than 3,400 failed banks and the ratings these institutions received shortly before folding simply overwhelms any defense of the usefulness of CAMELS."


"This isn't a matter of implementation or execution. The problem is the system itself... 

The U.S. needs a new, 21st century model for identifying, monitoring and reporting risk. It should be transparent to bankers, depositors, and investors in bank equity and debt.  The new model should be based on objective measures."

But Mr. Parsons suggests a solution...

Saturday, August 20, 2016

It's Hard To Be Robustly Humble...


Economic Truth Decay!
John Maynard Keynes, the eminent British economist, said: "If economists could manage to get themselves thought of as humble, competent people, on a level with dentists, that would be splendid!" 

But according to a recent blurb in The Economist, humility is not a growing phenomena among economists, who have come to believe they are superior.  Jokes Deidre McCloskey, an economic historian: "An economist will tell you with all the confidence of a witch doctor that interest rates will rise 56 basis points next month or that dropping agricultural subsidies will increase Swiss national income by 14.8%."
Cock-eyed, "which doctors"?

Kind of reminded me of the remarkable and consistent record of unreliability achieved by our economic pontificators, our "robusterian witch doctors" over on Duke Street, Alexandria. A well-signaled malpractice in any other profession - even at the novice or amateur level.


Makes one think that in terms of economic foresight and quantitative analysis the NCUA is...  

Friday, August 19, 2016

The Sun Also Rises.....


Guidance: "DUCK!"

Was really thrilled and certainly grateful for the "guidance" recently provided to credit unions on hurricanes and floods by the folks over on Duke Street.  It had never occurred to me that the NCUA was a noted authority and a point of reference on the topic of disasters, but come to think of it... 


U.S. Economic Forecast??

Did know that they had hired a slew of economists (about $2 million bucks worth!) to help assist the Federal Reserve with national economic planning.  So, perhaps the natural extension of that logic was to add a staff weatherman and meteorologists to help the National Weather Bureau with its forecasts.  The reliability and precision of economic and weather forecasts are, after all, "robustly correlated". 


Diaster Central Command Post
When you establish a clear record of competence and expertise; it's only natural to want to share those gifts with others.  And, NCUA has most definitely established quite a reputation for competence and expertise over the last decade...


Here's the NCUA's new official disaster guidance:

  • Implement pre-disaster actions to ensure a constant state of readiness.
  • Communicate disaster preparedness and response efforts before, during, and after an emergency.
  • Utilize a cross-section of people to develop, test, and implement disaster preparedness and response plans.
  • Ensure back-ups are available.
  • Treat disaster preparedness and response plans as living documents.


Wow!....

Thursday, August 18, 2016

Banzai...!!!


... means you never have
 to say (or admit!)
you're "sorry".

It is increasingly obvious that senior level failures at the Agency are squelched, white-washed, veiled and varnished - never to be acknowledged, all without consequence.


Which is why the NCUA is one of the few places in all the world, where you can meet....

Friday, August 12, 2016

Without a Shadow Of A Doubt...


The Agency has just released its latest video on enterprise risk management for credit unions.

"We are pleased once again to be at the very  forefront of risk management with robust analyses of potential risks which you would never ever have thought about without our help.  When we worry, you should worry!"


After all, we must protect the NCUSIF; folks would think we weren't competent if we bankrupted the Fund again!  


So, we're out to identify any and all risks; and, to make sure that you write a plan to manage each of them. 

Remember, NCUA is a stakeholder in your credit
union! We must manage your credit union while you write plans, since you don't have time to manage while you're writing plans... which come to think of it, sounds like another risk for which you should plan.

                                                                                           But, before we do that new plan, here's the new video from the Agency entitled:  

"A New, Dark Risk Every Credit Union 
Should Fear"

Saturday, August 06, 2016

"1984": Very Un-Appealing .....


Was a bit surprised the other day to find that some folks may "not get it" on a reference to "1984"! Maybe that's just someone "showing their (lack of) age" or perhaps it's a sign of something a bit more dire...
The novel "1984" was written by George Orwell in 1949 and forecast a future world (to occur around the year 1984) in which "things were never quite what they seemed". The book starts off with the classic opening line:  " It was a bright, cold day in April and the clocks were striking thirteen." 

If you have ever encountered the phrases: "Big Brother is watching you"; "newspeak"; "thought crime"; "double think"; "2+2=5"; or "Room 101"; they all came out of Mr. Orwell's book "1984"!  In fact, the whole spectre of a world gone mad on rigid government control and arrogant political correctness is often now described as "Orwellian"!


When the "thought police" dictate what you do, how you do it, and even what you should think; you have arrived at "1984"!  And, should you have the audacity to ask for an explanation - "to question authority" - then you are taken to "Room 101" where:

"There are three stages in your "reintegration"... There is learning; there is understanding; there is acceptance."

Until recently - the last three months to be precise - it appeared that we had arrived at that "un-appealing" 1984 point at the NCUA. 

Here was the Agency's attitude about proposed legislation (H.R. 3461) which would permit banks and credit unions to have a formal, legal right - and defined process - to raise grievances against inappropriate examiners. NCUA Executive Director, brother Dave Marquis, had this to say - not too long ago - about NCUA's concern over potential examiner accountability......

Wednesday, August 03, 2016

What Really Counts...


Robusterian quants - les grosses tetes-a-pointe - are particularly peculiar individuals, who are quite often remarkably deficient in their personal communications skills. 

They assume that their inherently idiosyncratic, articulatory amphigory speaks for itself - which usually, it most amusingly does!

But, the real problem is that their awkwardness with language "is positively correlated" with their clumsiness with math - with a high degree of confidence!
 (Your standard deviants aside!)


Let me give you an example of a heads-of-point conundrum with which the robusterians just can not abide. The serious analysis begins with the question: "How much is 1+1?"

Robusterians, of course, answer disdainfully that 1+1 = 2... all but the foolish (... and NCUA believes all of us are!) know that - right! "Elementary, my dear Watson!"


Well, try this.   If you were to take 1 wad of gum...

Wednesday, July 27, 2016

Lend Me An Ear ...


Never have liked folks who always whine and
complain; so instead of just grousing about the potential problems with risk-based lending, thought I'd offer up some more positive solutions to boost your credit union's lending... 


Has your loan-to-share ratio plummeted to a new low?  Is your expense ratio getting as tight as your teenager's jeans?  No problem.  Here are ten time-tested, sure-fire methods of increasing loans, boosting profitability and protecting your bonus:
    
1) Lower Credit Standards:  Just a little, it won't hurt (much!). You've tightened up too much, stimulate a little demand! C'mon take a walk on the supply side!

2) Make Long-Term Fixed Rate Loans - and Book'em!:  Drop the paternalism; stop trying to give members what they need - give 'em what they want!  Earnings will be great; and you've been around long enough to "time the market" and sell early before the upturn!
3) Offer Incentives for Loan Officers:  Heck, the more the merrier!  You want performance?  You gotta pay these days to create a little excitement and to spark their interest - especially their "self" interest and "conflict of" interest! 
4) Purchase Loans from Out-of-State Lenders:  Claim it's diversification and book some great up-front fees too! You can really spread your risks by having a few bad loans in every state!
5) Develop a Taste for Loan Participations:  The rates and terms are simply fantastic!!!!
6) Buy Asset-Backed Securities and Novel
Derivatives:  Innovation is the key to our future success and "synthetic" loans are the future.  Can't miss with this!  The underlying assumptions are absolutely empirical!  The brokers just exude confidence and they must know what they're doing, 'cause Guccis, Rolexes, and gold chains ain't cheap!
7) Trumpet Credit Cards:  Stop whining about bankruptcy, your members aren't worried about it!  Why be such a stick-in-the-mud?  Credit cards aren't any more dangerous than handguns!
8) Make Commercial Loans:  There isn't any real difference between consumer loans and commercial loans; same process, just much bigger bucks!  Let's stop hitting singles and swing for the fences!
9) "Sell" Loans To The Membership:  Don't you want to help cure this recession?  Let's help members shop 'til they drop! Nobody said their entire head had to be above water; keep lending until you can't see their noses!
10) Make Indirect Car Loans:  We're losing market share!!!  If the member is going to get shafted anyway, the least we can do is make it convenient!  Get in bed with these guys; sleep around a little; it won't hurt their reputation.


But for the very best professional advice, check around Monte Carlo or on the beaches of Jamaica where the "best and brightest" lending gurus  live very comfortably; circling like sharks, the "scent of  blood" rising from "lending innovations" now once again surfacing within the credit union movement....


Monday, July 25, 2016

Risk-Based Lending... In A Political Year


So, how can you support both Dennis Moriarity's and Gregg Stockdale's views of risk-based lending?

Isn't that like saying you are going to vote for Hillary Clinton and Donald Trump in the upcoming Presidential election?


X@*!!^

Let's take the second question first - that ain't funny!!!


One can support both Gregg and Dennis, because Gregg is right on the "macro" level and Dennis is equally right on the "micro" level. What does that mean? 


Well, using a large ("macro") pool of folks
(millions and millions of borrowers) for the analysis - the basic technique the Fair Isaacs Company ("FICO") uses - the statistics are right! In our example yesterday, one in five (20%!) of the folks in the queen/jacks pool are highly likely to become delinquent and perhaps "default" (which is defined as being past due 90 days or more). So, Gregg is dead on!


But, looking more closely at the "micro" (small) level - looking at each of the individual members of the queen/jack group - it becomes very clear that if the queen can be identified as the culprit "defaulter" then the jacks "statistically" will not default. FICO says empirically that not everyone in the group defaults - only 20% will, the jacks will repay and not default.  So, as Dennis points out, why do we overcharge the jacks (80% of the group!)... and also penalize them on their insurance, housing, employment....

In the macro world of finance you can legally
and logically use risk-based lending to charge much higher rates to our "queen /jack" group even though you know that approach "over-rewards" the queen - she does default and doesn't pay the higher rate! - and overcharges the jacks who do meet their obligations and do not default! It's unfair to everyone when you look at it that way!

So, although risk-based lending may be legal and "logical", the question for credit unions - who are owned by those queens and jacks - is are we willing to take some extra time to take a "micro" look at our members to try and improve the fairness of the lending process (and substantially lower their borrowing cost!), or are we going to continue to act like we don't know...

Sunday, July 24, 2016

A Really Bad Deal.... From A Stacked Deck! One For Dennis Moriarity and...


THIS ONE'S FOR DENNIS MORIARITY!
(... and Gregg Stockdale!)

Many financial institutions in the U.S. have in the past been
lured into practicing risk-based lending.  Some were just flat-out duped and fooled; while others - willing victims - really didn't mind playing the fool at all.  

Lot's of money can be made fleecing the poor with risk-based lending. "The empirical legitimacy" which misapplied mathematics provides the practice, makes the shearing of the sheep mere child's play - easy pickings!!  And generally, when given a choice between "good and gold"... well, you know how that usually comes out these days!

In risk-based lending, credit scores are used to establish a rate chart with members with lower scores paying higher rates. The statistically valid idea is that if lower credit scores create higher loan losses, then those members causing the losses should reasonably be charged for those higher losses. No problem with that.....
.... except that it's a lie.  
Let me show you clearly why.


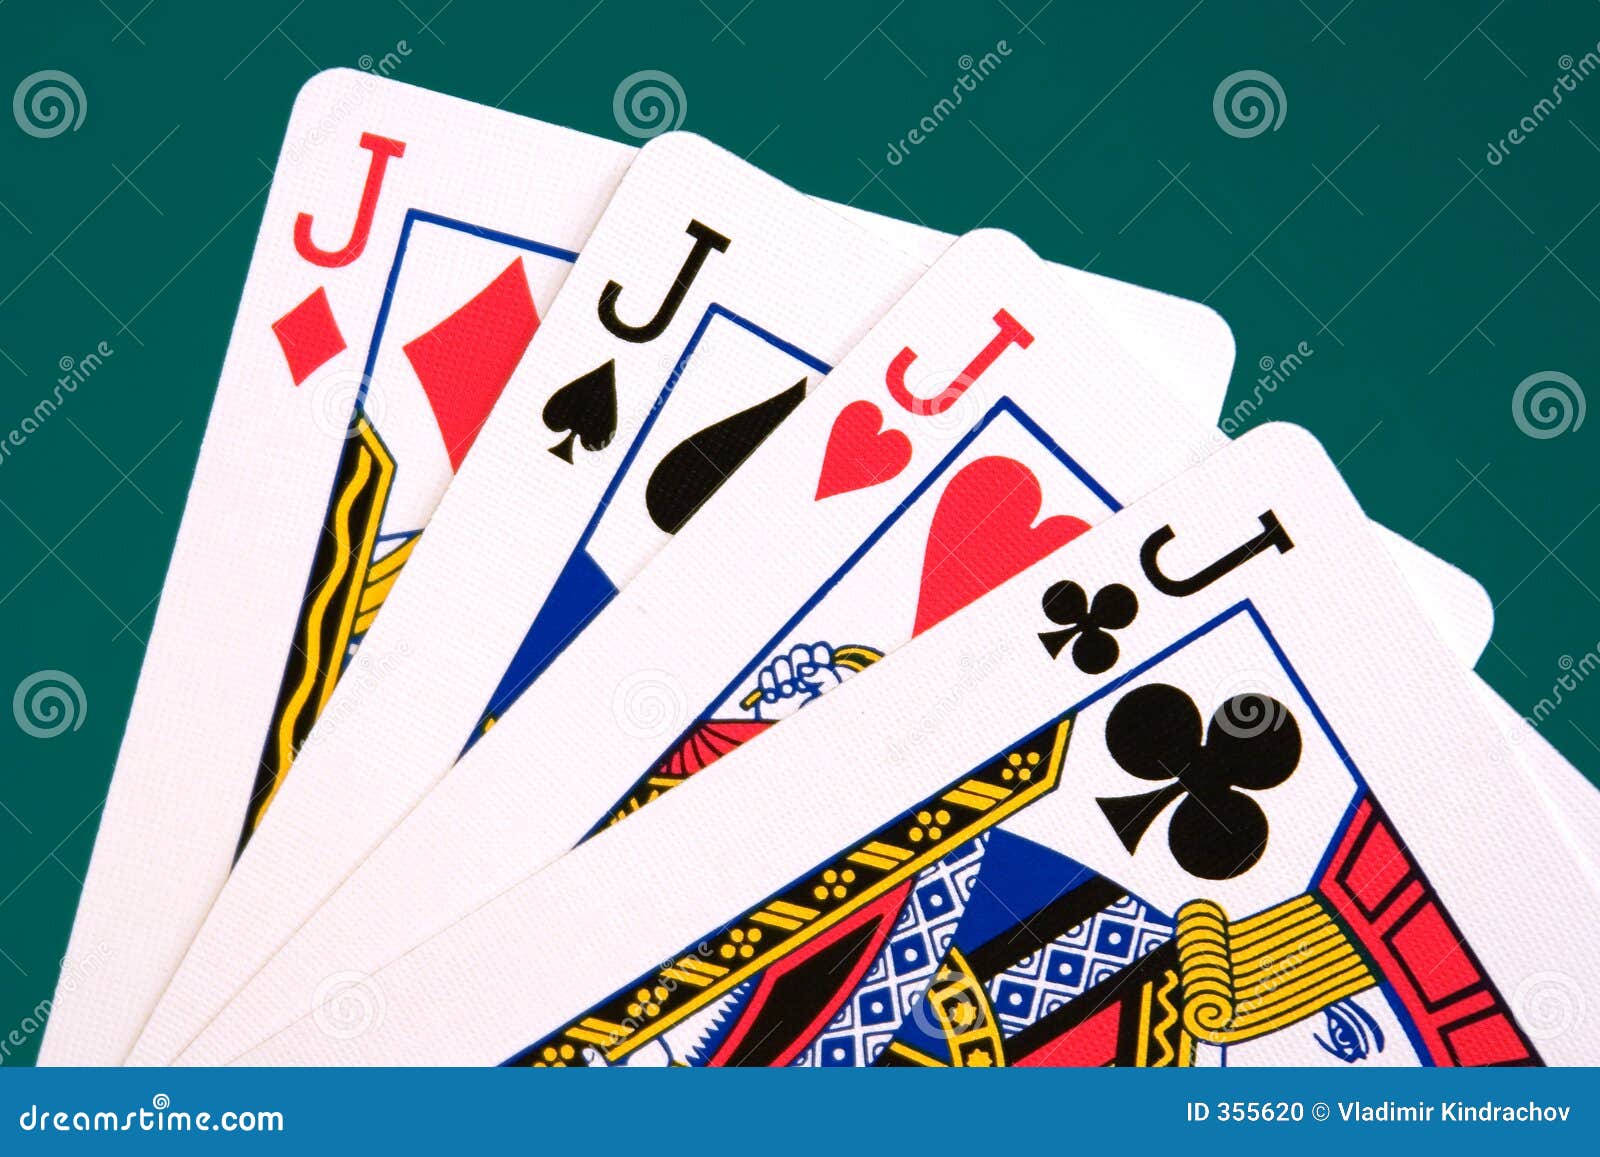
See the five face-down cards below? There are 4 jacks and a queen in the hand.  All five represent regular working folks, who all have low credit scores of 580, which implies that 1 in 5 (20%) of these folks will default on their loan over the next 24 months..  All are, therefore, charged the highest ("E-paper") interest rate.  Let me help you with a surefire fact, out of the 5 cards - the queen is the card ( the 20%), the 1 in 5 which will default in the future.
Pick the Queen!
Your odds are 1 in 5.


Now just for the sake of argument, let's assume you used a bit more rational, fair and defensible method of determining the actual risk of the borrower, rather than just "eenie-meenie" or "pick a card".   

Imagine that you actually sat down with each applicant individually and went over their financial condition, asked for explanations of the credit blemishes, and listened to them honestly as fellow members and human beings. Through the face-to-face interview and additional information gleaned, here's what the five borrowers look like to you:
Pick the Queen!
Too simplistic you say!  No not really.... it works in real life.... if you want it to....

But lots of folks don't want it to work.  Why?  Because the four jacks, with that old bad queen gone, are now "statistically certain" to pay, won't cause a loss, and deserve a much better rate.  You won't be able to statistically discriminate against them any longer and there goes the business plan, there goes the "bottom line", there goes the bonus....

Risked-based lending is a statistically "stacked deck", a bad hand, an unfair deal, a falsified game of chance played ruthlessly and recklessly against good-hearted, member-borrowers....  


And you hold all the cards!


But wait a minute, just a minute, whose credit union is it anyway?

Saturday, July 23, 2016

The Robust Theory Of Risk-Based Lending ...


An economy on the edge...!
In this economy, if you, as a consumer, have recently experienced a couple of those unfortunate, unexpected, "real-world, real-life" financial flareups don't despair! Proponents of risk-based lending (RBL) know how to help you get out of trouble!  

According to risked-based theorists, the best answer for those on the "financial ropes" is to offer you a loan with a higher rate!  If you can't handle the regular rate,  "upping the ante" is bound to enhance your ability to repay - right?  


'Ya follow that logic, don't 'ya?!?


These guys have come up with "a new financial life preserver" for those who are economically "drowning".   
Here it is...

Friday, July 22, 2016

A Robust Pause for the Weekend...


Let's take a bit of a breather -OK?  
Need a day or
two to digest the approved NCUA Strategic Plan. But for all the disenchanted NCUA naysayers, I hope you will at least acknowledge the many "greenshoots" you see budding from the recent actions of the NCUA Board - they may not blossom, but there has been a noticeable turn towards Spring.


Getting a handle
on VaR...

Couple of folks have asked: What's with the "VaR - (Vacuous and Robust !)" phrase?,  which was used in a recent send-up of the not-so-funny  misapplication of statistics and economic modeling by one of our favorite groups from Never-Neverland - those  prognosticating, robusterian gnomes. 

Well, you already know that vacuous means "empty, thoughtless" and robust means "written by an idiot"; so I assume the question is about "VaR".


Here's what the "Financial Times" says about VaR - or "Value at Risk":

"Value at risk are economic models which have been a key part of banks' and regulatory risk management toolboxes for the last two decades, despite being heavily criticized for failing to predict the large losses incurred during the financial crises."

"The models attempt to forecast how much money banks could lose from operations, lending, and trading, within a certain time frame, by overlaying historic market movements with statistical analysis."


Economic "Quacks" should fear
Black Swans and other B.S. including their own ....
Sounds like gobbledygook I'm sure, but the focus of the FT article ("Bond Yields Threaten Risk Models") was that models were once again demonstrating that they in fact can not correctly anticipate nor accurately forecast future markets - despite the "seemingly sophisticated", but repeatedly faulty, mathematical/statistical window dressing .

But, so what...

Sunday, July 17, 2016

NCUA: An Agency at the Crossroads... Part VI


This "stuff" is making
my head hurt !!

Realize that bombarding you with a history lesson (but remember we're talking about "history" which occurred just last year!) on the RBC meltdown was way too lengthy!  Sorry, but as they often say :


"It takes a long time for the truth to catch up with a lie".


To summarize…

We've seen that NCUA's
"Looked like a Croc!"
staff-sponsored risk-based capital (RBC) rule: 1) gutted the competitiveness of credit union lending and investments, 2) added substantial, unnecessary financial costs to credit union members, 3) underhandedly attempted to rewrite federal law as it applies to credit union "net worth" statutes, and 4)
effectively "gave the finger to Congress" and our Constitutional system of "checks and balances" (other than that the RBC proposal was a work of "great" merit!).


"Untruth and Consequences"
But, let's stop with the whining and cut to the chase. NCUA's senior staff was - after an unnecessarily expensive, time-wasting, politically embarrassing two year outcry by the entire credit union community - forced to recant and rewrite the RBC rule. The final RBC rule which passed in 2015 was realigned with professional national and international regulatory practices... but it was only done over the stonewalling, "we-always-know-better-than-you", infuriating noblesse oblige of the NCUA senior staff.


And, where is "the leadership" who "crafted" the disaster called "RBC1"? And, do you think... 

... they've changed their minds... or their "attitude"?

Friday, July 15, 2016

NCUA's Risk-Based Capital (RBC) Rule....


ALRIGHT, THE COMMENT PERIOD HAS OFFICIOUSLY ENDED...


 ... and the skill, wisdom, leadership, and exceptional grace which went into drafting the rule are painfully apparent to all.


  OK, SO NOW...

Risk-Based Capital: Commenting on Your Future - Part 5: OVERRIDING CONGRESS!

BLAST FROM THE PAST!
(originally published 3/26/2014)

... in which NCUA moves from rule making to lawmaking!

Really can't believe this !
Little different tack today in terms of reviewing NCUA's member-punitive and professionally embarrassing proposed, risk-based capital (RBC) regulation.  

We have taken a look at how NCUA's "we-know-better-than-everybody-else-despite-our-track-record" approach to RBC will 1) deter member mortgage lending, 2) damage MBL lending, and 3) severely limit safe CU investments, forcing unnecessarily lower savings returns on CU members.  All proposed with utter disregard for the new, lower RBC standards now already in place for all other federally insured depository institutions. 

Today let's look at how NCUA has decided to independently override the U.S. Congress and federal law with the new RBC proposal.  Have always noted how proud NCUA was of being "an independent agency of the Federal government", but it had never occurred to me that NCUA believes it is independent of Congress - and above the law.


Congress is such a bother to
 an independent federal Agency!
Here's how NCUA intends to override Congress. In Section 216 of the 1998 Credit Union Membership Act ("HB 1151"), Congress specifically and purposefully wrote into the Federal Credit Union Act (FCUA) a series of mandatory "net worth" categories and prompt corrective action (PCA) requirements.  Congress defined statutorily that a credit union was "well capitalized" if its net worth was >7%, "adequately capitalized" if its net worth was >6% but <7%, etc - five categories in all. Congress wrote into the FCUA statute a very, very clear definition of "net worth" - nothing accidental nor haphazard about what Congress meant by "net worth", nor how it was to be used to determine CU capital levels. 


NCUA through a sleight-of-hand (which they hope you won't notice!) has rewritten the Congressional definition of "well-capitalized" for CUs. 


Let's take a look at the proposed RBC reg:

Risk-Based Capital: Commenting on Your Future - Part 4: THE NCUSIF DEPOSIT FIASCO


BLAST FROM THE PAST!
(Originally published 3/24/14)
... in which NCUA even writes itself off!


Regulatory accounting:
Paper, rock, scissors? 
One of the positive requirements of the proposed NCUA risk-based capital (RBC) rule is that credit unions must comply with "generally accepted accounting procedures" (GAAP) -  except, of course, when NCUA chooses to make up its own accounting rules

Under NCUA's RBC rules, credit unions are required to "write-off" their 1% deposit which funds the cooperative deposit insurance fund (NCUSIF). But NCUA attempts to make this "unaccountable" accounting "sound harmless".  NCUA misleadingly advises that it neutralizes the "write-off" by requiring credit unions to subtract it "from both sides of the balance sheet".


Who's the
"dim bulb"?
The "subtracting it from both sides of the balance sheet" indicates that NCUA is not very bright or, more likely, they think you aren't! 

Here's why…

Risk-Based Capital: Commenting on Your Future - Part 3: PENALIZING SAFE INVESTMENTS.


The Robust Wizards of OB
BLAST FROM THE PAST!
(originally published 3/18/14)

... where NCUA quadruples risk-weighting on some gov't bonds!

Well, welcome to "Day 3" in our review of NCUA's proposed regulation on risk-based capital (RBC) - part of a week long exploration of regulatory OB-tuseness.  

Might help to go back and take a quick look at the posts of 3/17/2014 and 3/18/2014 where we talked about how NCUA's proposed RBC rule will significantly increase the capital costs for credit unions and, therefore, the financial costs to members seeking mortgages and business loans from their credit unions.


What's "capital"?
Let's also do another quick review of that obscure, "sometimes-difficult-to-grasp" concept called "capital"!  Again, remember that when NCUA requires more capital for a CU service, NCUA is essentially mandating an increased "tax " or "fee" on the credit union member for that product or service.  NCUA simply, unilaterally, and seemingly without justification "makes up" and then imposes these "capital taxes" on you, me, and your members!  No dialogue, no research, no quantitative proof, and no accountability to Congress nor those taxed.

 What ever happened to : 


"NO TAXATION
 WITHOUT REPRESENTATION"?


Today, let's take a look at the capital tax penalties which NCUA is imposing on credit unions on the other side of the balance sheet, with CU investments…