Friday, August 05, 2016

What Are The Odds...?


Guess I should 'fess up that I am in Las Vegas (business of course!) which makes no sense at all for me, since gambling is the only vice I lack. 

Everyone I ask always claims that they "do pretty well at the tables" on their Las Vegas trips. I still wonder how those fabulous hotels can be built if folks are all doing "pretty well at the tables"?   Somehow that "analysis" doesn't seem to add up...


What Are The Odds ??      

Under-pinning the 
"sport" of gambling, 
most statistical analysis, interest rate risk measurement, and standard economic forecasting is some form of probability theory. 


Probability theory attempts to measure the degree of certainty - or uncertainty - which should be assigned to a given estimate.  How likely - or unlikely - is that forecast "to become true" ? How much confidence can one have that an analysis is valid?  In gambling and games of chance, understanding "the odds" can help limit your losses or improve your chances of success. We all also use probability theory in our daily lives: "it's 50-50"; "it's a slam dunk"; "it's worth the risk": 
"there's not a snowball's chance in..."  


Spin Doctors ??
Within the credit union world, we are being asked to perform ever increasing rounds of risk analysis and ALM modeling - consuming huge amounts of time and resources with little, if any, reliable gain in certainty or accuracy.  

But much is at stake in any challenge to the 
"all gnome-ing ones" from Big Blue. Putting "your cards on the table" can often become a "one-sided bet", a game of regulatory "roulette Russianne" - with a stacked deck and a rigged wheel of fortune !!


But whining aside, here's a probability question for you to pose to your examiner at your next exit interview...


Q:  Out of the full universe of statistical possibilities, what is the probability that the only folks who know how to run a credit union have all ended up working at the NCUA? 

Thursday, August 04, 2016

Lightening Strikes Twice?


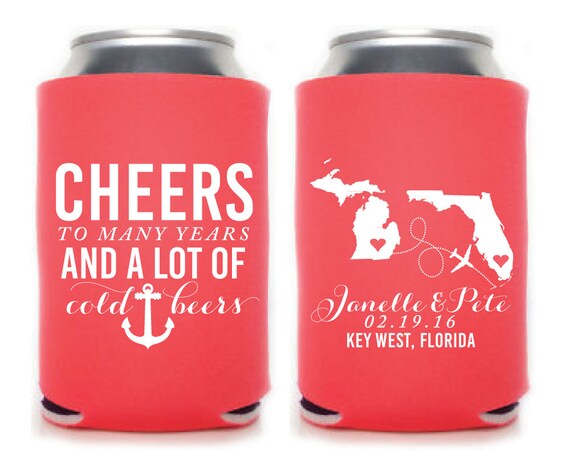
Was down at the beach in a rental and found myself in need of a "koozie".  Guess that koozies are everywhere. But for the uninitiated, a koozie is a little wrap-around that is useful to keep a bottle or can cool - if you are a sipper rather than a swigger. 
Sipper!

The difference between sipper vs. swigger? It is in technique. A sipper drinks with "the pouring hand" always daintily below nose level; the swigger pours with the hand above the nose, usually resulting in a temporary impairment of vision [and/or judgment!].
Swigger!

But, I digress. What I really wanted to tell you about was the koozie which I found in a bottom drawer.  It was one of those wedding koozies with an imprint showing the date and honoring the newly-wed couple. You've probably seen hundreds of them over the years, but this one was a bit different. Here's what it said:

Wednesday, August 03, 2016

What Really Counts...


Robusterian quants - les grosses tetes-a-pointe - are particularly peculiar individuals, who are quite often remarkably deficient in their personal communications skills. 

They assume that their inherently idiosyncratic, articulatory amphigory speaks for itself - which usually, it most amusingly does!

But, the real problem is that their awkwardness with language "is positively correlated" with their clumsiness with math - with a high degree of confidence!
 (Your standard deviants aside!)


Let me give you an example of a heads-of-point conundrum with which the robusterians just can not abide. The serious analysis begins with the question: "How much is 1+1?"

Robusterians, of course, answer disdainfully that 1+1 = 2... all but the foolish (... and NCUA believes all of us are!) know that - right! "Elementary, my dear Watson!"


Well, try this.   If you were to take 1 wad of gum...

Monday, August 01, 2016

Sunday, July 31, 2016

Saturday, July 30, 2016

Amazing Grazing....


NEWS YOU CAN USE:

The real Co-op !!!
"The Cooperative Extension Service will sponsor an "Amazing Grazing" workshop from 4-7 p.m. next Thursday.  The program will begin with an introduction to common forages and forage system alternatives and will follow with..."

Friday, July 29, 2016

Credit Unions: Lunatic Asylums...?


The tides - shaped by the Moon.
What shape is water? Ever thought about that? Probably not; and if you did, the answer is difficult to clearly fix. 

Water is weird; it comes in all shapes, forms, and sizes.  Highly unusual, different.  How strange!    

Every now and Zen it occurs to me that those people we label as less than mentally complete may be getting the short end of the stick. Perhaps, just perhaps their state of mind results from an inability to overlook reality, an inability to "rationalize", an inability to equivocate. 

Could their thinking be too clear?

... just different, too clear?

Perhaps, just perhaps they have never been desensitized and still can feel shocked, appalled, disgusted, and surprised. Perhaps, just perhaps they continue to unflinchingly notice that the world is not overburdened with logic nor compassion.

Perhaps, just perhaps they read their daily newspaper at full attention and watch television with their eyes and their minds wide open.  Perhaps, just perhaps they think the blood on the ground in a Syrian marketplace is real and that they are actually watching as a glazed-eyed child in Somalia dies of starvation.

And most maddeningly, perhaps, just perhaps they still think they ought to try to do something about it, even though they are aware that their best efforts may not alter the course of events.  
... or sit and object.

Is theirs' a continuing self-delusion that a sense of humanity demands that one try?  In the face of injustice do they still imagine that one is required to stand and object?


Well, what shape is water... ?

Wednesday, July 27, 2016

Some Really Good News!


Lend Me An Ear ...


Never have liked folks who always whine and
complain; so instead of just grousing about the potential problems with risk-based lending, thought I'd offer up some more positive solutions to boost your credit union's lending... 


Has your loan-to-share ratio plummeted to a new low?  Is your expense ratio getting as tight as your teenager's jeans?  No problem.  Here are ten time-tested, sure-fire methods of increasing loans, boosting profitability and protecting your bonus:
    
1) Lower Credit Standards:  Just a little, it won't hurt (much!). You've tightened up too much, stimulate a little demand! C'mon take a walk on the supply side!

2) Make Long-Term Fixed Rate Loans - and Book'em!:  Drop the paternalism; stop trying to give members what they need - give 'em what they want!  Earnings will be great; and you've been around long enough to "time the market" and sell early before the upturn!
3) Offer Incentives for Loan Officers:  Heck, the more the merrier!  You want performance?  You gotta pay these days to create a little excitement and to spark their interest - especially their "self" interest and "conflict of" interest! 
4) Purchase Loans from Out-of-State Lenders:  Claim it's diversification and book some great up-front fees too! You can really spread your risks by having a few bad loans in every state!
5) Develop a Taste for Loan Participations:  The rates and terms are simply fantastic!!!!
6) Buy Asset-Backed Securities and Novel
Derivatives:  Innovation is the key to our future success and "synthetic" loans are the future.  Can't miss with this!  The underlying assumptions are absolutely empirical!  The brokers just exude confidence and they must know what they're doing, 'cause Guccis, Rolexes, and gold chains ain't cheap!
7) Trumpet Credit Cards:  Stop whining about bankruptcy, your members aren't worried about it!  Why be such a stick-in-the-mud?  Credit cards aren't any more dangerous than handguns!
8) Make Commercial Loans:  There isn't any real difference between consumer loans and commercial loans; same process, just much bigger bucks!  Let's stop hitting singles and swing for the fences!
9) "Sell" Loans To The Membership:  Don't you want to help cure this recession?  Let's help members shop 'til they drop! Nobody said their entire head had to be above water; keep lending until you can't see their noses!
10) Make Indirect Car Loans:  We're losing market share!!!  If the member is going to get shafted anyway, the least we can do is make it convenient!  Get in bed with these guys; sleep around a little; it won't hurt their reputation.


But for the very best professional advice, check around Monte Carlo or on the beaches of Jamaica where the "best and brightest" lending gurus  live very comfortably; circling like sharks, the "scent of  blood" rising from "lending innovations" now once again surfacing within the credit union movement....


Tuesday, July 26, 2016

The Bargain Basement...


Mr. Filene
Been having several Edward Filene Moments over the last few days as the discussion gained heat on risk-based lending, but not the type you might suspect. 

'Course everyone associated with credit unions knows that Mr. Filene was the principal benefactor and key driving force behind the creation of the credit union movement in the U.S.

What many forget is that Mr. Filene was also a truly world class innovator  in "retailing" - the "Steve Jobs-like, marketeer extraordinare" of his era. His flagship store was Filene's in Boston and his "guy in a garage" retailing innovation incubator was the famous Filene's Basement.

Filene's was a creative sensation with an entrepreneurial spirit, which introduced many of the core sales techniques still used today, including "fixed price/same price" for all merchandising, "% OFF" discounts, "two-fers", closeout sales, and lay-away plans. Filene knew how to create sales excitement in the department store space and shopping frenzies! 

Part of Mr. Filene's great interest in the credit union movement was to help create a source of credit for working men and women, so that they could purchase some of the "small luxuries" in life "on installments." Fair and reasonably priced credit gave workers greater purchasing power, at places like Filene's Basement! Filene most certainly understood his business, but more importantly he understood human nature, which made his fortune!


But, in talking about risk-based lending and other recent "innovations" in the credit union movement, sometimes wonder how all this will turn out. 

Are we actually following in Filene's historical footsteps or have we become something quite different, but not different at all?